🚨 TRUMP DROPS A MASSIVE “MOST SUCCESSFUL” PRESIDENCY CLAIM — AND THE TIMING IS TURNING HEADS 😳
Trump Calls His Economy the 'Most Successful' in Presidential History — The Numbers Tell a Far More Complicated Story
The economy is still expanding, stocks are up and layoffs remain low. But 1.5% growth, sticky inflation, modest hiring and a $40 trillion debt make “greatest ever” a political slogan, not a measurable conclusion.
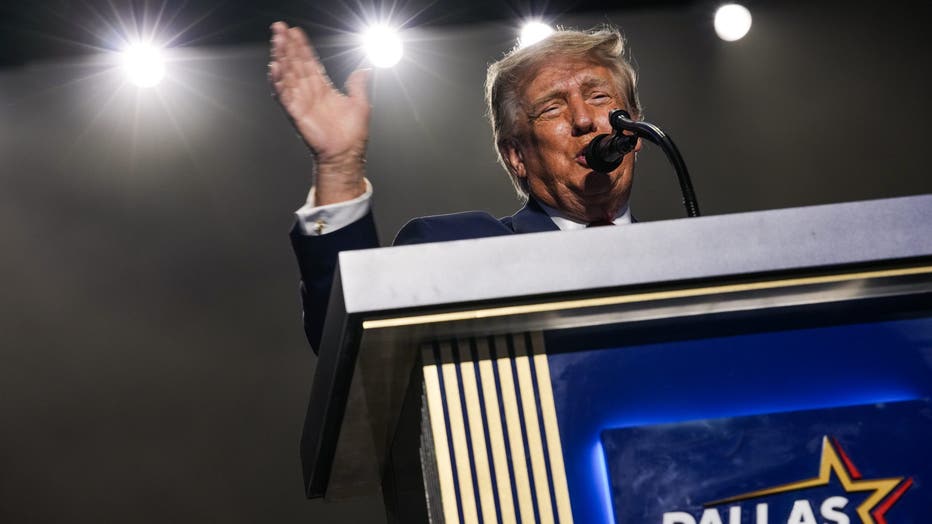
Donald Trump used the Republican midterm convention in Dallas to make one of the broadest economic boasts of his presidency: “This has been the most successful two years financially and every other way in the history of the presidency.”
It is a line built for a campaign stage. It is also nearly impossible to prove as stated. “Most successful” is not an official economic category, and there is no single government statistic that ranks presidencies that way.
The more defensible way to test the claim is to look at the actual scorecard. That scorecard is not catastrophic — but it is mixed enough that a sweeping “greatest ever” verdict outruns the data.
THE CENTRAL DISTINCTION: Trump is entitled to make a political argument about his record. But “the most successful presidency in history” is a subjective superlative, not an objective finding produced by the Bureau of Economic Analysis, the Labor Department, the Federal Reserve or any other economic authority.
There Are Real Positives — and They Should Not Be Waved Away
The United States is not in a declared recession. Real GDP has continued to grow, consumer spending remains an important source of demand, unemployment was 4.1% in August, and weekly jobless claims remain in a historically low range.
August payrolls also surprised to the upside, with employers adding 162,000 jobs. That matters because the labor market had spent much of the prior year looking unusually weak.
Financial markets give the White House another legitimate talking point. Major stock indexes remain positive for 2026, with the S&P 500 still up double digits for the year through September 11 even after a volatile week.
A fair assessment therefore cannot begin with the claim that nothing is working. The problem for Trump is different: the positive data points do not automatically add up to the best economic performance in American presidential history.
Growth Slowed to 1.5% in the Second Quarter
The Bureau of Economic Analysis estimates that real GDP grew at a 1.5% annualized rate in the second quarter of 2026, down from 2.1% in the first quarter.
Consumer spending strengthened, which is a real positive. But the overall growth rate slowed as government spending declined and investment and exports decelerated.
A 1.5% annualized quarter is expansion, not collapse. It is also not the kind of number that, by itself, establishes a historically unmatched boom.
GDP is only one measure of economic performance, and a single quarter should not be treated as the entire economy. But the latest official growth estimate is plainly inconsistent with portraying every major economic indicator as historically dominant.
Inflation Is Still Too High to Call the Cost-of-Living Fight Finished
The inflation picture is similarly mixed. In the latest second estimate for the second quarter, the PCE price index rose at a 5.3% annualized rate — revised up from the earlier 5.1% estimate — while core PCE rose at a 3.6% annualized pace.
The more familiar year-over-year consumer measure is less severe but still elevated: headline CPI was 3.4% in August, with energy prices up more than 16% from a year earlier.
Those two figures measure different things over different windows. The quarterly PCE rate should not be presented as if consumer prices were simply “up 5.3% over the year.” But both measures point to the same political problem: inflation has not disappeared.
Kevin Warsh, the Federal Reserve chair, now faces pressure in the opposite direction from the White House. Markets are preparing for the possibility of higher rates to restrain inflation, while Trump has continued pushing for lower rates.

The Labor Market Is Resilient — but Hiring Is Still Modest by Recent Standards
The strongest argument for economic resilience may be the labor market. Layoffs remain rare, and initial unemployment claims recently came in at 206,000 — still near historically low levels.
But hiring has been much less spectacular. Employers have added roughly 80,000 jobs per month so far in 2026, even after the strong 162,000 gain in August.
That is a meaningful improvement from the exceptionally weak pace of 2025. It is still below the roughly 166,000 monthly average recorded in 2023 and 2024.
Scott Bessent has correctly noted that more Americans are working than ever before. The missing context is that total employment normally reaches new highs as the population and economy grow. The harder question is how fast new jobs are being created.
Comparisons with Joe Biden also require care because the enormous hiring surge of 2021 and 2022 reflected the reopening from pandemic shutdowns. Even excluding those unusual years, however, recent job creation has been stronger than the 2026 pace so far.
Trump's $20 Trillion Investment Number Is Not an Established Fact
Donald Trump paired his “most successful” boast with another dramatic number, telling the Dallas crowd that more than $20 trillion in investment had been committed to the United States and suggesting the total could reach $25 trillion.
That figure has not been substantiated by a public accounting that supports the full amount. Independent fact-checking has found the White House’s own published investment tally to be much lower, and even that list includes pledges whose timing, enforceability and ultimate spending are not always clear.
Investment announcements can be economically meaningful. They are not the same thing as dollars already spent, factories already built or jobs already created.
An announced investment commitment is not identical to completed investment. Until the administration provides a transparent project-by-project accounting for the claimed $20 trillion-plus total, that number should be treated as a political claim rather than a verified economic aggregate.
The Debt Is Above $40 Trillion, and the Deficit Is Still Enormous
The federal fiscal picture is harder to square with the language of an across-the-board financial triumph. Total gross national debt stood at about $40.10 trillion on September 3, roughly $2.67 trillion higher than a year earlier.
The Congressional Budget Office estimates that the federal deficit reached about $2.0 trillion in the first 11 months of fiscal year 2026. That was roughly in line with the same period a year earlier — actually about $6 billion lower — but it remains an extraordinary amount of annual borrowing.
No serious accounting would assign the entire $40 trillion debt to Trump. It accumulated across many administrations and Congresses, Republican and Democratic, through wars, recessions, tax cuts, entitlement spending, emergency relief and rising interest costs.
But the debt cannot simply disappear from a claim about the country’s financial performance either. A presidency claiming unparalleled financial success still has to explain a government borrowing roughly $2 trillion in a single fiscal year.
Energy Prices Are Again Squeezing Household Budgets
Households are also feeling a fresh energy shock. The war with Iran and disruptions to global oil infrastructure have pushed crude prices above $100 a barrel, with U.S. gasoline averaging above $4 a gallon and diesel moving above $6.
That does not mean the president controls the global price of oil with a switch. Wars, shipping disruptions, refinery conditions, producer decisions and world demand all matter.
Politically, however, families experience the result at the pump and in freight-sensitive prices. A government can argue over causation; households still have to pay the bill.
The Stock Market Is a Genuine Strength — but It Is Not the Whole Economy
Trump can point to a strong stock market. The S&P 500 has set dozens of record highs since his second term began and remains substantially higher in 2026. Corporate profits and enthusiasm around artificial intelligence have helped support that rally.
Even here, precision matters. Trump has claimed 80 all-time stock-market records, while a recent count cited by the Associated Press put the S&P 500 at 66 record closes since the start of his second term.
More importantly, stock indexes measure the value of publicly traded companies — not whether every household can afford rent, groceries, health care, fuel or a mortgage. Market strength is part of the economic record, not a substitute for the rest of it.
Presidents Get Too Much Credit — and Too Much Blame
The broader truth applies to Trump as much as it did to presidents before him: the White House influences the economy, but it does not control it. Congress sets taxes and spending, the Federal Reserve sets monetary policy, businesses decide whether to hire and invest, and global shocks can overwhelm domestic plans.
That means critics should not pretend every negative number is personally manufactured by Trump. It also means the administration cannot reasonably claim sole ownership of every positive development, especially trends shaped by prior policy, private investment or global forces.
Economic credibility comes from applying the same standard in both directions.
'Most Successful Ever' Works Better as a Slogan Than a Statistic
There is a defensible pro-Trump economic case: no recession, low layoffs, a 4.1% unemployment rate, a strong August jobs report, resilient consumer spending and stock markets that remain well above where they began the year.
There is also a defensible skeptical case: GDP growth slowed to 1.5%, inflation remains above the Federal Reserve’s long-run goal, 2026 hiring has been modest by recent standards, energy costs have surged, the deficit is around $2 trillion and the national debt has moved above $40 trillion.
Those facts can coexist. That is precisely why the economy is better described as mixed and resilient than as an uncontested historical record.
The Strongest Defensible Conclusion
What is verified is that Trump made the “most successful two years” claim publicly in Dallas and can point to several genuine strengths, including continued growth, low layoffs and a strong stock market.
What is also verified is that the latest official data contain major complications: 1.5% second-quarter growth, elevated inflation, slower hiring than several recent years, a roughly $2 trillion fiscal-year deficit through August and gross federal debt above $40 trillion.
May you like
That does not prove the economy is failing. It does mean “most successful in presidential history” is not a conclusion the numbers independently establish.
Trump can campaign on the record. Voters can decide how much credit he deserves. But if the claim is “greatest ever,” the standard has to be more demanding than repeating the slogan until it sounds like a statistic.